The 2026 Top 100: Underlying Health Issues
Key Highlights
- Many leading companies experienced losses or valuation write-downs in 2025, reflecting industry-wide challenges.
- Overall sales of all the companies in the Top 100 increased by 2.4% - but so did food-at-home inflation, meaning zero volume growth.
- If you add them all up, net profits declined by $14 billion, indicating pressure on profitability despite revenue growth.
It’s been a tough year for (choose one):
A. Conagra Brands
B. Kraft Heinz
C. Molson Coors
D. All of the above
The correct answer, of course, is D – and the same could be said for several of the largest food & beverage companies in the U.S. and Canada. Eight companies from our annual Top 100 list lost money in 2025 or their most recent fiscal year, and five of those eight were in the top 24 companies. Does that say something?
Also in the red were big companies General Mills and J.M. Smucker; the other three money-losers were near the bottom of the list: B&G Foods, Monogram Foods and Utz Brands.
It also was a year for writing down the valuation of your company. Kraft Heinz, Conagra and General Mills all took special charges for that, which pushed all three into the red.
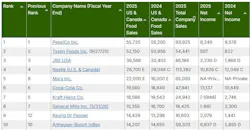
If you add up the sales of all 101 companies (there was a three-way tie for last place) in the chart on pp20-21, collective 2025 sales were $653.88 billion. Despite all the bad news over the past year, that’s a 2.4% increase from those same companies’ sales in 2024.
However, if you look at inflation in the past year, food-at-home prices rose an identical 2.4%. So one can presume that, collectively, this group had zero volume growth.
Another interesting computation: If you add the net income figures for 2025 vs. 2024, their profits were down $14 billion.
This is our Top 100 report, our annual list of the 100 (this year 101) largest food & beverage processors in North America and a mid-year checkup of the financial health of the industry. All the sales figures in this report represent only products made in U.S. and Canadian plants – we go to great lengths to calculate and isolate those numbers. However, net income is from the total or parent company, unless indicated otherwise.
To see last year's story, "Meh, Just an OK Year," click here.
Among all 101 companies, sales increased by at least 5% for 23 of them; decreased at least 5% for 12. Net income increased for 20, decreased for 24.
The top 25 companies were hardest hit in profits: only six improved net income while 12 regressed. But sales were up for 11 of those big companies, down for only four (“by at least 5%” in all cases).
What do all those numbers and computations mean? That it was a typical year for Big Food, with some companies continuing on a growth trajectory, a few even excelling (look at Coca-Cola’s and Keurig Dr Pepper’s numbers), and others taking the widely reported hits from private label, entrepreneurial small companies and economic factors like inflation and tariffs.
Throughout the past year or so, even when sales increased, for many the bumps were due to inflationary pricing, with volumes declining. Max Gumport, senior analyst with financial firm BNP Paribas, keyed on that issue: “With group volumes down for the fifth straight year and disruptors driving [approximately] 64% of industry sales and growth off just [approximately] 2% of sales, we believe the group must get disruptive and take greater action.”
To see Editor Dave Fusaro's commentary on the Top 100, click here.
Gary Stibel, founder & CEO of The New England Consulting Group (www.necg.net), adds, “The North American food & beverage industry still is healthy because Americans like to eat and drink. But the biggest brands and companies are not healthy.”
“The consumer is still hungry, just not for yesterday’s brands at tomorrow’s prices,” adds Ben Nobles, a principal with New England Consulting. “The middle is a really dangerous place to be these days.”
Back to Gumport: “To be sure, we recognize the group is not sitting still. Indeed, we commend the stepped-up investment posture shown by some companies. Still, we believe that more dramatic efforts, particularly around innovation, must be taken.
“The consumer is demonstrating a demand for food with certain qualities and attributes. While cutting prices helps to address the gap between value and price in the current food product offering, we believe the more sustainable approach would be to add more value to the food itself through disruptive innovation.”
The Top 100 (in brief)
Biggest winners and losers
Some of the biggest gainers, not surprisingly, were among the biggest companies. You know what happened to beef prices: JBS USA’s revenues increased by $4 billion, National Beef’s by $1.5 billion (extrapolated from parent company Marfrig Global Foods’ annual report). Bimbo Bakeries’ U.S. and Canada operations grew by $1.3 billion, according to our extrapolations from their Mexican parent’s annual report.
Mars’ sales jumped $6 billion (according to our estimate) – but that included the acquisition of Kellanova. Lactalis American Group increased by $1 billion, mostly due to the purchase of General Mills’ yogurt business. Keurig Dr Pepper grew by $1 billion also, aided by both organic growth and acquisitions.
Coca-Cola’s sales grew by $911 million, but more impressive was its net income: up by $2.5 billion. PepsiCo’s sales were virtually flat while its net shrank by $1.3 billion – although 2024 was an extraordinarily good year for the company.
At $113 billion in sales globally, Nestle SA is used to profits of more than $10 billion, and 2025 did not disappoint, although net did drop by $1.4 billion. Nestle is among a handful of companies reorganizing; just last month it spun off its global waters business.
Mondelez grew its global sales figure nicely, up nearly 6% to $38.5 billion. But it required a$1.7 billion windfall in European sales and a small bump in AMEA revenues to offset a $231 million drop in North American sales (to $10.7 billion) and a $27 million dip in Latin America. Maybe as a result, its net was halved to $2.45 billion.
The biggest reversal in sales belonged to Cal-Maine Foods. The country’s biggest egg producer had a blowout fiscal 2025 (which ended May 31, 2025), its sales nearly doubling to $4.3 billion, driven by last year’s skyrocketing price of eggs. Now that egg prices are low, sales for the fiscal year just ended are under $3 billion again. Net income was a quarter of what it was, too.
We thought we would be including two new companies to emerge from Kraft Heinz, but a new CEO called off that split. So you can’t blame him (Steve Cahillane) for another billion-dollar drop in revenue, nor for the $5.848 billion net loss for 2025, mostly the result of special charges and a write-down of the company’s market capitalization. Kraft Heinz’s U.S. and Canadian sales have been declining for six years in a row.
Conagra, too, has a new CEO (John Brase) and a $2 billion write-down of its valuation. General Mills took $1.8 billion in non-cash goodwill and brand intangible asset charges that led to its $88 million loss, the first in our memory, maybe the first ever.
Molson Coors went from a $1 billion profit in 2024 to a $2 billion loss last year. On the other hand, Constellation Brands had a $1 billion loss in 2024 -- because of the write-down of its investment in Canadian cannabis company Canopy Growth – but turned that into a $2.8 billion profit last year.
Two companies reported improved (but continuing) net losses last year. J.M. Smucker lost $1.2 billion in 2024 but only $139 million in its fiscal 2026, which ended April 30 of this year. B&G Foods trimmed its $251 million loss in 2024 to $43 million in red ink last year. About the same for Monogram Foods.
Comings and goings
Every year we add a company or two or delete some. Some venerable old names are no longer with us, WK Kellogg Co and sister Kellanova foremost among them. Hain Celestial, in an effort to be less diversified, sold off many food brands and just missed making this year’s list.
This may be the last year for Unilever on our list. Hopefully by this time next year, virtually all of Unilever’s foods will be part of a much larger McCormick & Co. Plus, Unilever last December spun off its ice cream business into Magnum Ice Cream Co. (which debuts at No. 69), and that sucked $2 billion out of the parent’s sales.
We’ve wrestled in the past with the inclusion of BellRing Brands, the mostly powdered protein spinoff of Post Holdings, but we’ve included it this year at No. 66. Ditto for Del Monte Corp., which just missed making previous lists but this year lands at No. 72 with the reunification of Fresh Del Monte Produce with most of the former Del Monte Foods business.
Hearthside Food Solutions is a shadow of its former self, but, according to our estimates, still makes the list, however as renamed No. 58 Maker’s Pride. Another old company with a new name: Lancaster Colony Corp. changed its name to Marzetti Co.
With some recent acquisitions, Sigma Foods makes the list at No. 85. Same story for Simply Good Foods (No. 88). And Canada Packers (No. 91) was spun off from Maple Leaf Foods last year, so it makes the list as a separate food processor.
About the Author
Dave Fusaro
Editor in Chief
Dave Fusaro has served as editor in chief of Food Processing magazine since 2003. Dave has 30 years experience in food & beverage industry journalism and has won several national ASBPE writing awards for his Food Processing stories. Dave has been interviewed on CNN, quoted in national newspapers and he authored a 200-page market research report on the milk industry. Formerly an award-winning newspaper reporter who specialized in business writing, he holds a BA in journalism from Marquette University. Prior to joining Food Processing, Dave was Editor-In-Chief of Dairy Foods and was Managing Editor of Prepared Foods.